Property cash flow determines outright approval for DSCR and non-QM investment loans, but it plays, at best, a supporting role in conventional underwriting. The two paths ask completely different questions: DSCR lenders want to know if the property pays for itself, while conventional lenders want to know if you, personally, can cover the debt. Before you apply anywhere, check whether your file will be judged on rent or on your tax returns.
TL;DR:
- Most DSCR loan programs require a minimum ratio of 1.0 to 1.25, with better rates and higher LTVs available for ratios above 1.25.
- Lenders often base rent calculations on Schedule E net income or appraiser’s market rent, applying a 75% haircut for appraisals to account for vacancies and expenses.
- Proper documentation such as signed leases, reserve verification, and timely appraisal ordering can prevent delays and improve approval chances.
- Higher property cash flow allows for better pricing tiers, higher LTVs, and lower reserve requirements, especially when documenting stronger rental income or reducing loan size.
- Matching the loan program to the specific file conditions, such as LLC vesting or low reserves, can significantly improve approval likelihood and loan terms.
Table of Contents
- The Role of Property Cash Flow in Loan Approval: DSCR vs. Conventional Underwriting
- How Lenders Calculate Qualifying Rental Income
- Documentation and Appraisal Mechanics That Make Cash Flow Count
- How Cash Flow Shapes Pricing, LTV, and Reserves
- Steps to Strengthen Your File Before You Apply
- How The Texas Mortgage Pros Matches Cash-Flow Files to the Right Lender
- Get Your DSCR or Rental Cash Flow File Reviewed
- Sources
- FAQ
The Role of Property Cash Flow in Loan Approval: DSCR vs. Conventional Underwriting
Two underwriting models dominate investment property financing, and knowing which one a lender uses tells you exactly what documents to gather.
DSCR underwriting looks only at the property. Lenders calculate the debt service coverage ratio by dividing gross monthly rent by the full monthly PITIA (principal, interest, taxes, insurance, and association dues). Most DSCR programs set a minimum ratio between 1.0 and 1.25, meaning the rent needs to equal or exceed the payment by that margin. Sub-1.0 and no-ratio options exist, but they usually come with tighter credit, reserve, or down payment requirements to offset the added risk.
Conventional underwriting works the other way. It verifies your personal income, calculates your debt-to-income ratio, and pulls two years of tax returns and Schedule E history to see how rental properties have actually performed on paper.
Investors tend to move toward DSCR programs when:
- They vest title in an LLC, and conventional lenders won’t approve entity ownership
- Tax returns show limited taxable income due to depreciation and write-offs
- They’ve hit the loan-count caps that agency lenders impose on individual borrowers
If none of those apply, conventional financing often still wins on rate and cost. If any of them do, DSCR is usually the faster and only realistic path.
How Lenders Calculate Qualifying Rental Income
The rent figure a lender uses to run your numbers isn’t always the rent you actually collect. It depends entirely on the documentation path.
- Schedule E qualifying. Lenders start with the net rental income reported on your tax return, then add back non-cash and financing expenses, including depreciation, mortgage interest, HOA dues, property taxes, and insurance, to reconstruct a more accurate picture of cash flow.
- Lease or appraiser market-rent qualifying. When a Schedule E history doesn’t exist yet, or a lender wants a forward-looking figure, they’ll use the current signed lease or an appraiser’s opinion of market rent from Form 1007 or Form 1025. In this path, lenders commonly apply a 75% haircut to gross monthly rent to account for vacancy and operating expenses, per Fannie Mae guidance.
- Owner-occupied vs. pure investment treatment. If you’re buying a multi-unit property and living in one unit, the rules shift again: PITIA gets allocated differently, and net rental losses can offset qualifying income rather than boost it.
The gap between these methods matters.
Documentation and Appraisal Mechanics That Make Cash Flow Count
The appraisal often carries more weight than anything else in the file. Lender commentary on DSCR underwriting mechanics consistently points to the market-rent schedule as the figure that ultimately drives the DSCR calculation, especially on purchase transactions where no lease history exists yet.
Underwriters typically request:
- Signed leases or a current rent roll for occupied units
- Schedule E filings for properties with rental history
- Bank statements verifying reserves
- LLC operating agreements, articles of organization, and EIN letters when the property vests in an entity
Pro Tip: Order your appraisal early and pull comparable rent data from local listing sites beforehand. Appraiser market-rent opinions often fall short of what investors project, so having your own comps ready gives you a stronger position to challenge a low number before it derails your DSCR.
Common conditions that stall closings include missing proof of insurance, outdated bank statements, and unresolved title exceptions. Respond promptly to these issues, and you’ll avoid the single biggest cause of delayed closings on cash-flow-based files.
How Cash Flow Shapes Pricing, LTV, and Reserves
Stronger property cash flow doesn’t just get you approved. It changes the loan’s price and terms.
DSCR lenders typically price in tiers, so a ratio of 1.25 unlocks better rates and higher loan-to-value than a ratio of 1.0. Practitioner guidance on DSCR pricing notes that even a marginal DSCR improvement, achieved by documenting an extra $100 in monthly rent or slightly trimming the loan size, can shift a file into a better pricing tier and save real money over the life of the loan.
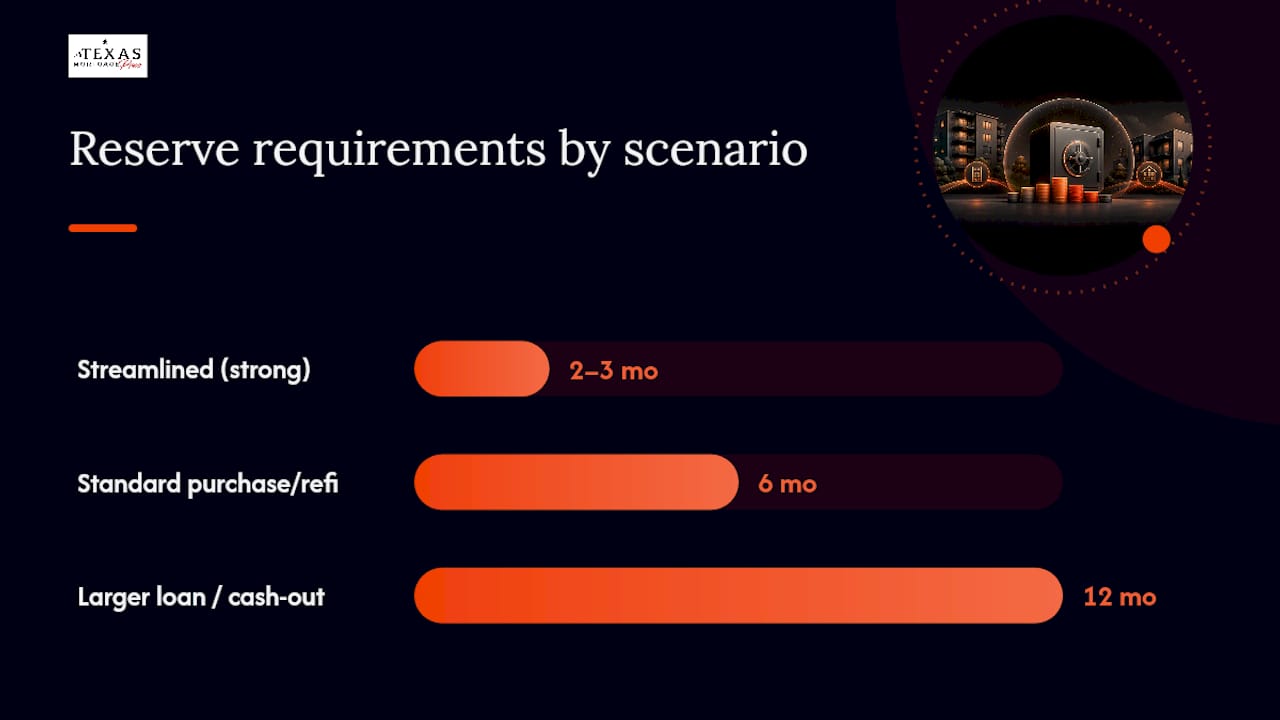
Reserve requirements move with risk, too:
- Standard purchase or refinance transactions often call for 6 months of PITIA in reserves
- Larger loan amounts or cash-out refinances can push that to 12 months
- Some streamlined programs on strong files accept as little as 2 to 3 months
Lenders will also let you offset a weak DSCR with a higher FICO score, a larger down payment, or additional reserves. That tradeoff works, but it usually comes at the cost of a higher rate or a lower maximum LTV than a file with strong cash flow.
Steps to Strengthen Your File Before You Apply
Small adjustments made before submission often matter more than anything you can negotiate afterward.
- Lock in lease documentation. A signed 12-month lease at market rent gives underwriters a cleaner number to work with than a month-to-month tenant or a vacant unit awaiting an appraiser’s opinion.
- Order the appraisal with a market-rent request explicitly attached. Confirm your appraiser will complete Form 1007 or Form 1025 rather than a standard form without the rent schedule.
- Build reserves beyond the minimum. Extra months of PITIA in the bank can offset a borderline DSCR and keep your file out of higher pricing tiers.
- Consider a larger down payment. Reducing loan size directly improves your DSCR by lowering the PITIA denominator.
- Time your credit pulls. Multiple inquiries in a short period can dent your FICO score right when you need the best pricing tier available.
- Verify entity documents in advance if vesting through an LLC. Missing operating agreements or EIN letters are a common last-minute holdup.
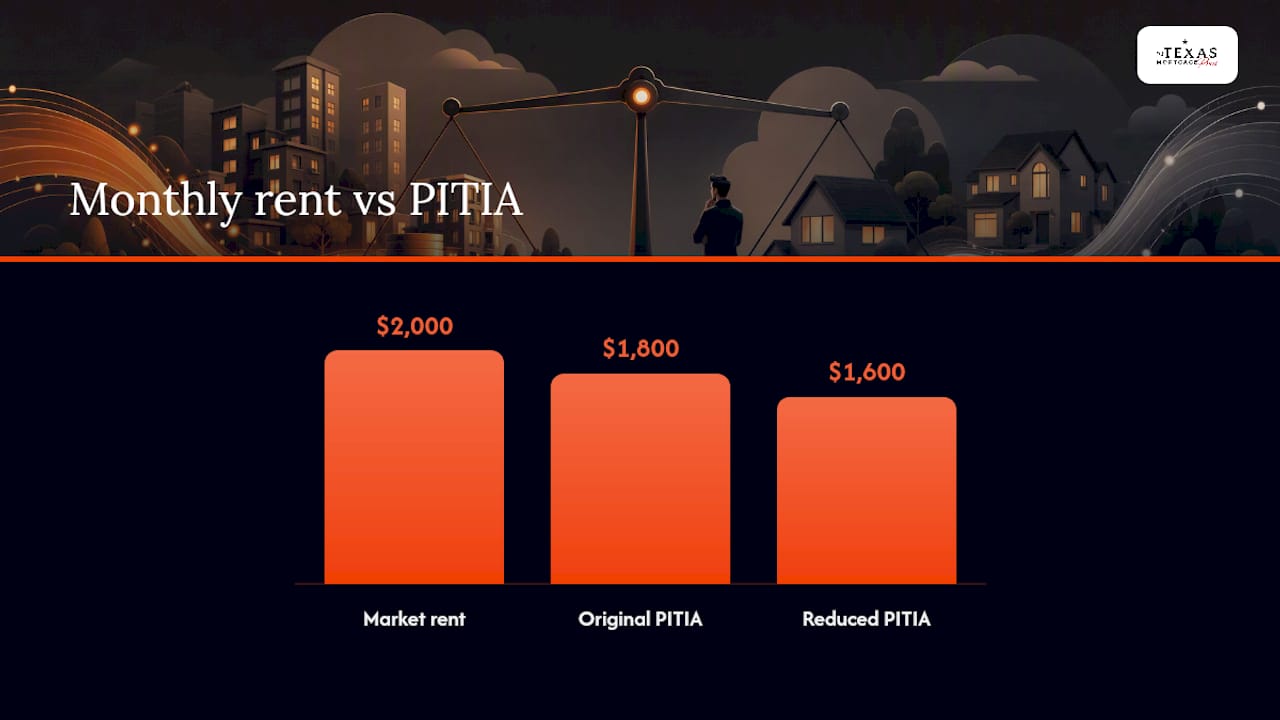
Consider a property renting for $2,000 a month against a $1,800 PITIA. That’s a 1.11 DSCR; workable, but not top-tier. Increase the down payment enough to drop PITIA to $1,600, and the ratio jumps to 1.25, likely moving the loan into a better pricing bracket. Investors who can document high existing rental income and don’t need entity vesting are usually better served by preparing full conventional documentation, since agency pricing still tends to beat DSCR pricing when you qualify for it. Landlords looking to boost the rent figure itself before applying can also find practical tactics in strategies for maximizing rental income, from tightening turnover time to repricing units to local market rates.
Pro Tip: Run your numbers through a DSCR calculation before you ever talk to a lender. Knowing your ratio in advance tells you whether you’re negotiating from strength or walking into a conversation about compensating factors.
How The Texas Mortgage Pros Matches Cash-Flow Files to the Right Lender
Not every lender treats rental income the same way, and matching a file to the wrong program wastes weeks. A mortgage brokerage that works with a large network of lenders can often find a better fit for a DSCR file that gets declined or repriced at one shop, without having to start the application over.
That range matters most on borderline files: reserve shortfalls, entity vesting questions, or a DSCR just under a pricing-tier threshold. Careful document review upfront, leases, Schedule E history, reserve statements, catches the gaps that typically generate underwriting conditions later, which keeps closings moving instead of stalling on avoidable requests…
Get Your DSCR or Rental Cash Flow File Reviewed
Running the DSCR math yourself is a good start, but knowing which of 70-plus lenders will price your file best is where the real savings show up. Comparing mortgage programs side by side can help a rental property with a tight ratio or an LLC vesting structure land with a lender built to underwrite that situation, rather than getting declined by one that isn’t.
Whether you’re testing a purchase scenario or refinancing an existing rental, start by running your numbers through the mortgage calculators to see how rent, down payment, and PITIA interact before you apply. When you’re ready to move forward, request a personalized rate quote and get matched to a program suited to your property’s actual cash flow.
Sources
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
FAQ
Does property cash flow always determine loan approval?
No. It’s decisive for DSCR and non-QM investment loans, but conventional loans weigh personal income, DTI, and credit history first, with rental cash flow playing a secondary role.
What DSCR ratio do I need to qualify?
Most programs set the minimum between 1.0 and 1.25, though sub-1.0 and no-ratio options exist with stricter credit and reserve requirements.
Why would an appraiser’s rent figure be lower than my actual lease?
Lenders often apply 75% of gross monthly rent from Form 1007 or Form 1025 appraisals to account for vacancy and expenses, which typically produces a more conservative number than your signed lease.
How many months of reserves do DSCR lenders require?
Reserve requirements typically range from 2 to 12 months of PITIA, depending on the loan size, purpose, and the strength of the rest of the file.
Can I use an LLC to hold the property and still qualify for a DSCR loan?
Yes.